Quick Answer
To get out of poverty, work on five things at the same time: lower your biggest fixed costs (usually rent and car payments), raise your hourly pay by learning one in-demand skill, pay down high-interest debt with a clear method, claim benefits you already qualify for such as the Earned Income Tax Credit (EITC) and SNAP, and track your net worth every month. Specific changes in these areas move you forward far faster than cutting small expenses like coffee.
If you’re living paycheck to paycheck, “save 10% of your income” is advice that doesn’t fit your reality, because 10% of nothing is still nothing. Most people stay stuck for structural reasons: fixed costs that swallow most of each paycheck, an income ceiling that extra hours can’t break through, and debt that grows faster than it can be paid off.
This guide explains how to get out of poverty by attacking those three barriers directly, with practical steps you can start this week. It focuses on what individuals and families can do. If you want the bigger, policy-level picture, read our companion article, How to Fix Poverty: What the Evidence Shows.
Table of Contents
Step 1: Cut Your Biggest Fixed Cost First, Not Your Smallest
Generic advice tells you to skip coffee or cook at home more. Those habits help a little, but for most low-income households, housing and transportation are by far the largest monthly expenses. That is where real savings are found.
The U.S. Department of Housing and Urban Development (HUD) considers a household “cost-burdened” when it spends more than 30% of its gross income on housing, and “severely cost-burdened” above 50%. If your rent is above that 30% line, you are structurally behind before the month even starts. Moving to a cheaper unit, taking on a roommate, or moving closer to work to cut commuting costs will usually save more than any coupon strategy.
Car payments matter just as much. According to Experian, the average new-car payment was about $765 a month in mid-2026, and the average used-car payment was about $531. On a $35,000 salary, a $400 to $500 car payment can be the single biggest reason you can’t build savings. If you’re shopping for a car, a reliable used vehicle bought with a smaller loan is almost always the better move.
Step 2: Raise Your Hourly Value With One In-Demand Skill
Working two minimum-wage jobs trades time for money at a fixed rate. There are only so many hours in a week, so this approach has a hard ceiling, and it often leaves no time to build skills that pay more.
What actually moves income is raising your hourly value through one marketable skill. Good options include commercial driving (CDL), phlebotomy, medical billing and coding, HVAC repair, and welding. Training time varies: some programs, like CDL and phlebotomy, can be finished in a few weeks to a few months, while trades like HVAC and welding typically take several months to about a year. None of them require a four-year degree or large student debt.
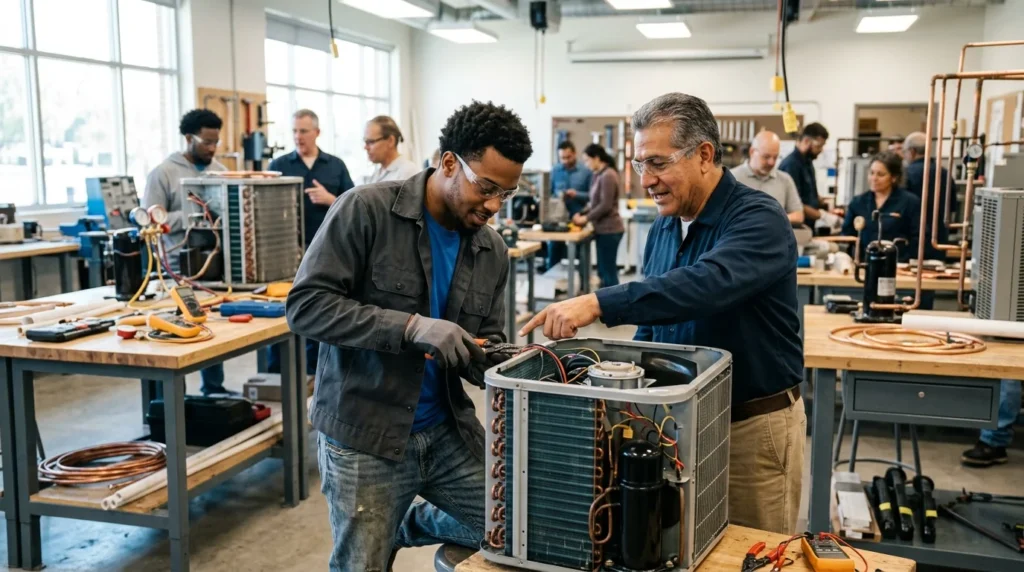
Many of these programs are free or heavily subsidized for low-income applicants through federally funded American Job Centers, community colleges, and local workforce development boards. Search “workforce development board” plus your state and your target trade, or visit CareerOneStop to find the nearest American Job Center. Nonprofits can also help: Darul Infaq’s Educational Assistance program helps students from low-income families cover tuition, books, and exam fees.
Step 3: Use Debt Strategically Instead of Avoiding It Entirely
Credit card debt with interest above 20% actively works against you. The fastest way to pay it down is the avalanche method: pay the minimum on every balance, then put every extra dollar toward the debt with the highest interest rate first.
If you need motivation more than math, use the snowball method instead: pay off your smallest balance first, then roll that payment into the next smallest. Consumer research has found that people who focus on clearing individual balances are more likely to stick with their repayment plan, even though the avalanche method saves more in interest overall. The best method is the one you will actually follow.
Not all debt is bad. A low-interest loan for a certification that raises your income by $8,000 a year belongs in a completely different category from a payday loan. The question to ask is simple: will this debt increase my income or reduce my costs by more than it costs me?
Step 4: Claim the Benefits You Already Qualify For
Many families leave money on the table simply because they never apply. The Earned Income Tax Credit (EITC) is a refundable federal tax credit for low- to moderate-income workers, and the IRS estimates that about one in five eligible workers miss out on it each year. For tax year 2025, the maximum credit is $8,046 for families with three or more qualifying children, and income limits go up to $68,675 for married couples filing jointly. For tax year 2026, the maximum rises to $8,231 and the top income limit to about $70,244. You must file a tax return to receive it, even if you don’t normally need to file, and free filing help is available through the IRS Volunteer Income Tax Assistance (VITA) program.
SNAP (food assistance) and WIC (nutrition support for pregnant and postpartum women, infants, and children under five) free up cash that would otherwise go to groceries. You can also dial 211 to reach local United Way and community resources for rent, utility, and emergency help that are easy to miss in an online search.
Charitable organizations can fill the gaps that government programs leave. Darul Infaq provides Financial Assistance for essential living expenses, Monthly Groceries for families facing food insecurity, and Emergency Relief when an unexpected crisis hits. For Muslim families in need, our guide on who is eligible for Zakat explains who can receive this form of support.
Apply even if you assume you won’t qualify. Income limits are often higher than people expect, especially for households with children.
Step 5: Track Your Net Worth, Not Just Your Paycheck
Your paycheck tells you what you earned. Your net worth tells you whether you’re actually moving forward. To calculate it, add up your savings and any assets, then subtract your total debt. Check that number once a month.
If your net worth is rising, even slightly, your plan is working, even when your bank balance still looks scary the day before payday. If it’s flat or falling despite full-time work, something in your fixed costs or debt structure needs to change now, not eventually.
Mistakes That Keep People Stuck in Poverty Longer
Using payday loans and car title loans. According to the Consumer Financial Protection Bureau (CFPB), a typical two-week payday loan with a $15 fee per $100 borrowed carries an annual percentage rate (APR) of almost 400%. On a $300 loan, that’s $45 every two weeks; roll it over for a full year and you could pay about $1,170 in fees without touching the original $300. Car title loans are similarly expensive and can cost you your car. Avoid both, even when a bill feels urgent. Calling the utility company to set up a payment plan is almost always cheaper.
Co-signing loans for family members. When you co-sign, you are legally responsible for the full debt. If the other person misses a payment, it damages your credit score, not just theirs.
Ignoring your credit score. Your score directly affects what you pay to borrow. Experian data from mid-2026 shows borrowers with prime credit (661 to 780) paid about 6.15% on new-car loans, while subprime borrowers (501 to 600) paid about 13.52%. On used cars, the gap was even wider: about 8.81% versus 19.10%. That difference can add up to several thousand dollars over the life of a single loan.
How Darul Infaq Helps Families Move Toward Self-Reliance
At Darul Infaq Foundation, we believe the goal of charity is not lifelong dependence but dignity and independence. Alongside immediate help like Fresh Meals and groceries, our Self-Reliance Projects give families the initial support, resources, and guidance they need to build a stable, independent future. If you or someone you know needs help, contact our team.
The Path Out of Poverty Is Specific, Not General
Poverty isn’t solved by willpower or by cutting lattes. It’s solved by lowering fixed costs, raising your hourly income through one real skill, using debt strategically, claiming the assistance you already qualify for, and tracking real progress through your net worth. Pick one of these five steps this week and make one concrete change, whether that’s checking your EITC eligibility, calling your local workforce board, or asking for a lower rent quote.
Small, specific actions compound faster than any generic budgeting advice ever will.
Calculated your zakat on gold? Pay it where it reaches those who qualify.
Give Your Zakat Now →Frequently Asked Questions
What is the fastest way to get out of poverty?
The fastest results usually come from reducing your largest fixed cost (often rent or a car payment) while claiming every benefit you qualify for, such as the EITC and SNAP. Over the medium term, learning one in-demand skill that raises your hourly pay creates the biggest lasting change.
Can you get out of poverty with a minimum-wage job?
It is very difficult with minimum wage alone, because extra hours have a hard ceiling. Most people who escape poverty combine lower fixed costs with short, low-cost training that leads to higher-paying work.
Is the snowball or avalanche method better for paying off debt?
The avalanche method (highest interest first) saves the most money. The snowball method (smallest balance first) helps many people stay motivated. Choose the one you are most likely to stick with.
Where can I get financial help if I am struggling?
Start with government programs like the EITC, SNAP, and WIC, and dial 211 for local resources. Nonprofits like Darul Infaq also offer financial assistance, groceries, and emergency relief for families in need.